

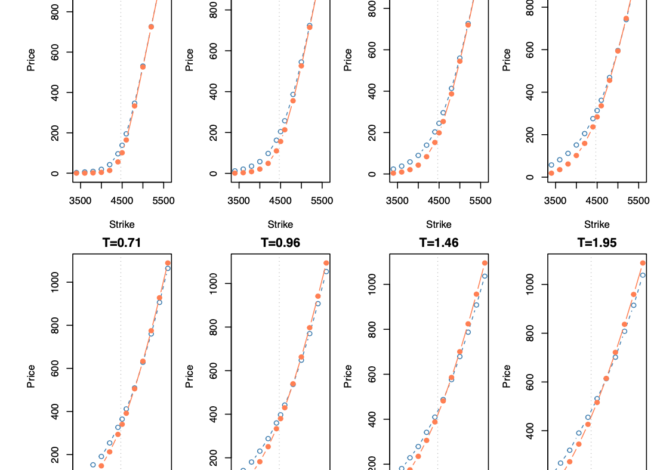
Semi-parametric option pricing based on underlying’s historical data (accepted at the osQF 2026 (ex R/Finance) conference)
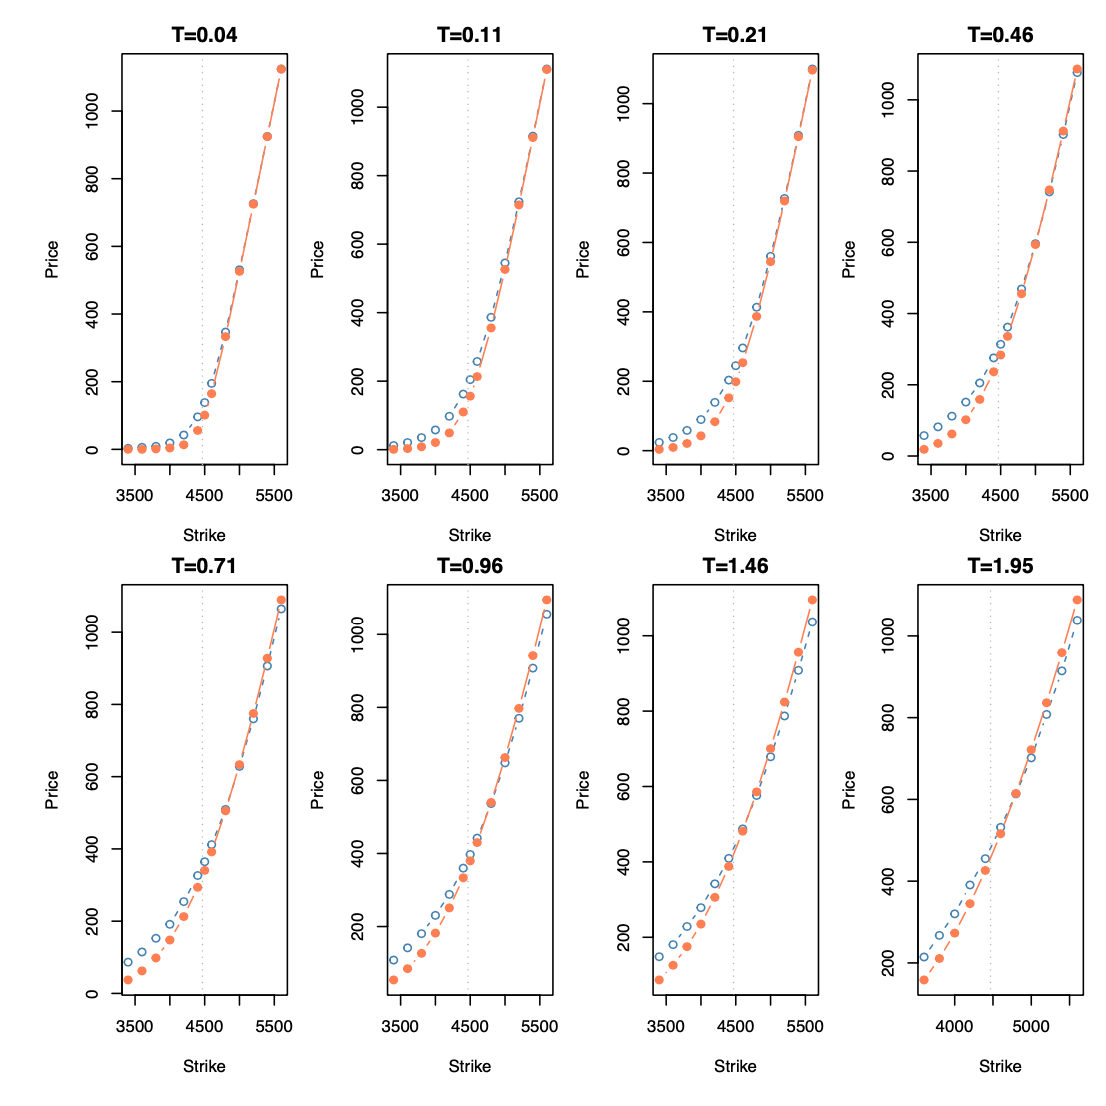
This post is a follow-up to my previous posts on semi-parametric option pricing. A link to the study (accepted for presentation at the osQF 2026 conference) is provided at the end of this post. In this study (R code provided), we build an empirical pricing measure for options directly from their underlying’s historical dynamics, requiring […]
4 mins read